Most parents are excited to give their children a head start. So it is jarring to watch some of them turn down a free $1,000 investment in their own baby’s future because they don’t like the name on the account.
Trump Accounts, created by Congress in last year’s tax law (the Working Families Tax Cuts), give every eligible child born from 2025 through 2028 a $1,000 federal deposit, invested in a broad list of American companies. Yet surveys this year found that roughly one in eight parents plan to skip it because they disapprove of the Trump administration. Tax preparers, including from the National Association of Tax Professionals, report hearing the same objection from their clients.
Whose money is it?
Let’s be clear about whose money this is. It isn’t any President’s. Congress appropriated it, and taxpayers, including the very parents refusing it, are paying for it either way. Once a parent claims the account, grandparents, employers, and others can contribute up to $5,000 a year, and philanthropists Michael and Susan Dell pledged $6.25 billion toward millions of children’s accounts. The money sits in a low-cost index fund until the child turns 18, when it becomes the child’s own retirement account.
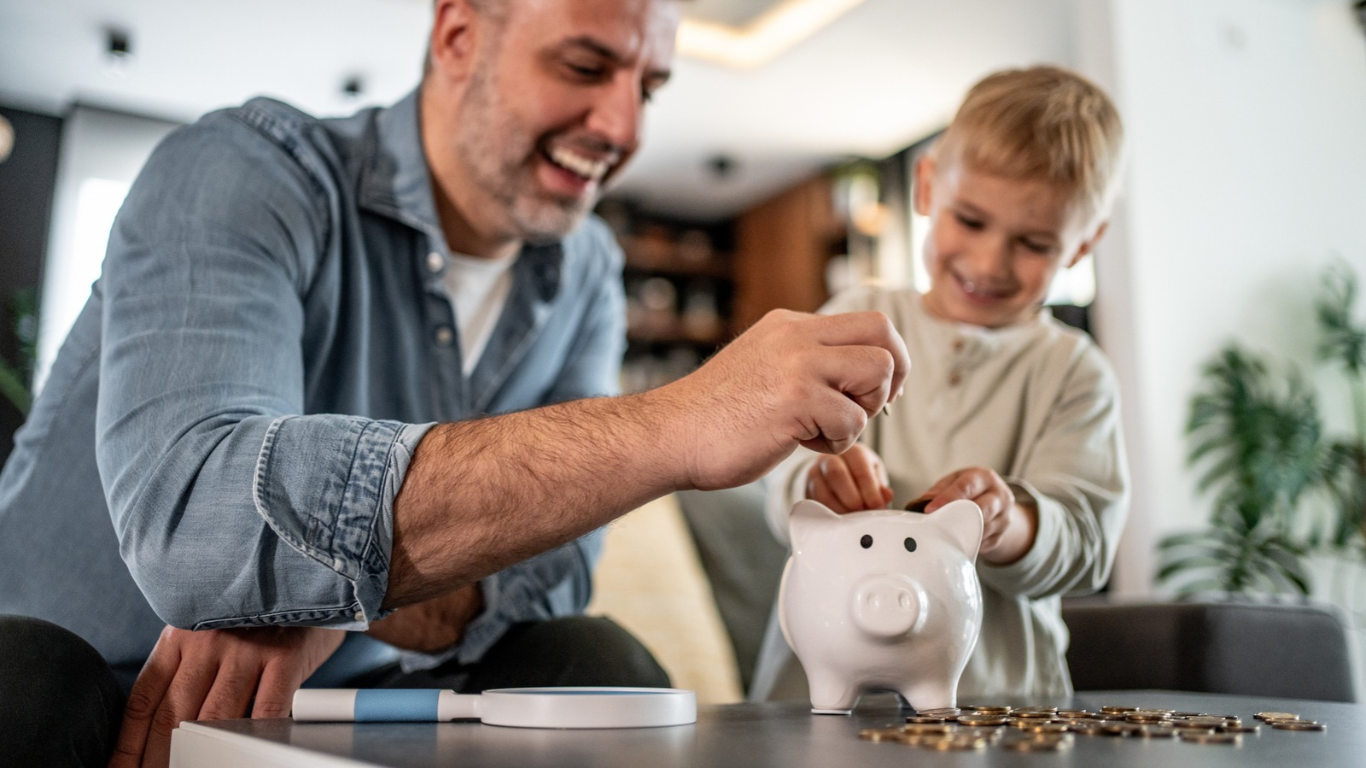
Time is a valuable tool in investing. A thousand dollars set aside at birth and left alone for 18 years can grow multiple times. With maximum family contributions, White House economists estimate an account could top $300,000 by age 18. Each year a parent waits is growth a child never gets back.
Children aren’t a protest weapon
Parents are entitled to their politics. But a child’s savings account isn’t a ballot box. A newborn has no opinion about who sits in the Oval Office, and today’s President will be long gone by the time that child decides whether to spend the money on college, a business, or a first home. Refusing the deposit doesn’t cost President Trump a thing. It only shrinks the resources a child can access for young adulthood.
Caring for future generations means putting their long-term interests ahead of adults’ short-term squabbles. It’s the same instinct that leads families to save for college or buy life insurance. These accounts also give parents a hands-on way to teach children about saving and the power of compound growth, a lesson too few young Americans learn.
Independent Women has been supportive of Trump Accounts since their inception as a tool of giving the next generation a jumpstart on a bright future.
Even leaders who agree with the President on almost nothing make this point. Gov. Gavin Newsom (D-Calif.) urged families to sign up, calling the accounts one of the best things Trump has done. Sen. Cory Booker (D-N.Y.) teamed up with Republicans to recruit corporate contributions and praised the accounts for building on his own “baby bonds” idea.
Claim it
Parents with an eligible child can claim the account through the Treasury’s official app. The account may already exist, but the $1,000 isn’t automatic: a parent must claim it. Social Security is even sharing enrollment information through hospitals and newborns’ card mailers. If parents also want to save through a 529 plan, do both. They aren’t mutually exclusive.
To parents who still object to the name: take that up with Congress. Just don’t make your child pay for your disagreement.